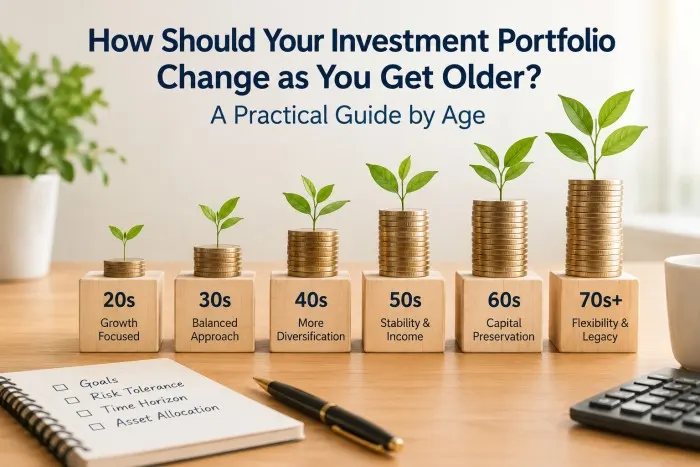
How Should Your Investment Portfolio Change as You Get Older? A Practical Guide by Age

Building an investment portfolio is not a one-time decision. As age, income, financial responsibilities, and retirement goals change, the balance between growth and stability may need to change as well. A portfolio that makes sense in the early stages of a career may not be appropriate when retirement is approaching.
The goal is generally to balance the opportunity for long-term growth with the need to manage investment risk. Understanding how asset allocation can evolve by age can help investors review their strategy more thoughtfully.
In Your 20s: Focus on Long-Term Growth
Investors in their 20s often have several decades before retirement. This long time horizon can provide greater flexibility to tolerate short-term market fluctuations.
A portfolio at this stage may place a larger portion of assets in stocks or stock-based funds because equities have historically provided greater long-term growth potential than many lower-risk investments. Bonds, cash, and other relatively stable assets can still have a role, particularly for emergency savings or near-term financial goals.
The key advantage at this stage is time. Regular contributions and reinvesting investment returns can allow compound growth to work over many years.
In Your 30s: Balance Growth With Financial Responsibilities
During the 30s, income may increase, but expenses can also become more significant. Home purchases, family expenses, education costs, and other financial commitments may affect how much can be invested and how much risk feels appropriate.
A growth-oriented portfolio may still make sense for long-term retirement savings, but diversification becomes increasingly important. Investors can review their exposure to stocks, bonds, and other asset classes while making sure their overall investments align with their goals.
This is also a useful period to increase retirement contributions when income rises rather than allowing lifestyle expenses to consume every increase in earnings.
In Your 40s: Review Risk and Diversification
The 40s can represent an important transition point. Retirement may still be 15 to 25 years away, but the investment horizon is shorter than it was earlier in life.
At this stage, investors may begin gradually increasing the allocation to bonds or other less volatile assets while maintaining sufficient exposure to growth investments. The appropriate mix depends on retirement timing, savings, expected income, and individual risk tolerance.
For educational resources and financial planning information, companies such as The Motley Fool provide material covering portfolio allocation and retirement strategies.
Regular portfolio reviews are particularly useful during this period. A portfolio can become unintentionally concentrated when certain investments outperform others, making rebalancing an important consideration.
In Your 50s: Prepare for the Retirement Transition
Once investors reach their 50s, protecting accumulated wealth becomes increasingly important alongside continued growth. Retirement could be only a decade or so away, meaning there may be less time to recover from a significant market decline.
A gradual shift toward a more balanced portfolio may help reduce dependence on stock-market performance. However, moving entirely out of stocks may create another risk: insufficient growth to keep pace with inflation during a potentially long retirement.
Investors can also consider how much money will be needed during the first several years of retirement. Keeping an appropriate amount in relatively liquid and stable investments may help cover near-term expenses without requiring the sale of growth assets during a market downturn.
In Your 60s: Focus on Income and Capital Preservation
For people entering retirement in their 60s, portfolio priorities often become more focused on generating sustainable income and managing withdrawals.
A diversified portfolio might combine stocks for long-term growth with bonds, cash, and other assets intended to provide greater stability. The exact allocation should reflect expected retirement expenses, other income sources, tax considerations, and personal risk tolerance.
It is also important to consider sequence-of-returns risk. Significant investment losses early in retirement can have a greater impact when withdrawals are being made at the same time.
In Your 70s and Beyond: Maintain Flexibility
Age alone does not determine the right portfolio allocation. People in their 70s and beyond can have very different financial circumstances, life expectancies, spending needs, and sources of income.
Some retirees may need substantial growth exposure to support a retirement lasting several decades. Others may prioritize stability because they have limited tolerance for market declines.
Regular reviews can help ensure the portfolio remains aligned with changing expenses, required withdrawals, estate-planning objectives, and broader financial circumstances.
Why Asset Allocation Should Not Be Based on Age Alone
Age-based investing can provide a useful starting point, but it should not be the only factor considered. Two people of the same age can require very different investment strategies.
Important considerations include retirement savings, expected Social Security or pension income, debt, emergency reserves, investment experience, tax situation, health and longevity considerations, and the amount of income needed from investments.
Risk tolerance also matters. An investor may have the financial capacity to accept market volatility but may not be comfortable experiencing large portfolio declines.
Rebalancing Matters at Every Age
Portfolio allocation can change naturally as investments perform differently. If stocks rise significantly while bonds remain relatively stable, the portfolio may become more stock-heavy than originally intended.
Rebalancing involves reviewing the portfolio and bringing its asset mix back toward the intended allocation. This does not necessarily mean making frequent changes. A scheduled annual review or another consistent approach may help investors avoid making emotional decisions based on short-term market movements.
The Bottom Line
Investment portfolios often evolve as retirement gets closer. Younger investors may have more capacity to emphasize long-term growth, while those approaching or living in retirement may place greater emphasis on diversification, stability, income, and managing withdrawals.
There is no single asset allocation that works for everyone at a particular age. Instead, age can serve as one useful reference point alongside financial goals, time horizon, risk tolerance, income needs, and overall financial circumstances. Regular portfolio reviews can help keep an investment strategy aligned with those changing priorities.